Q3 Shipping Costs: A Tale of Elusive Savings
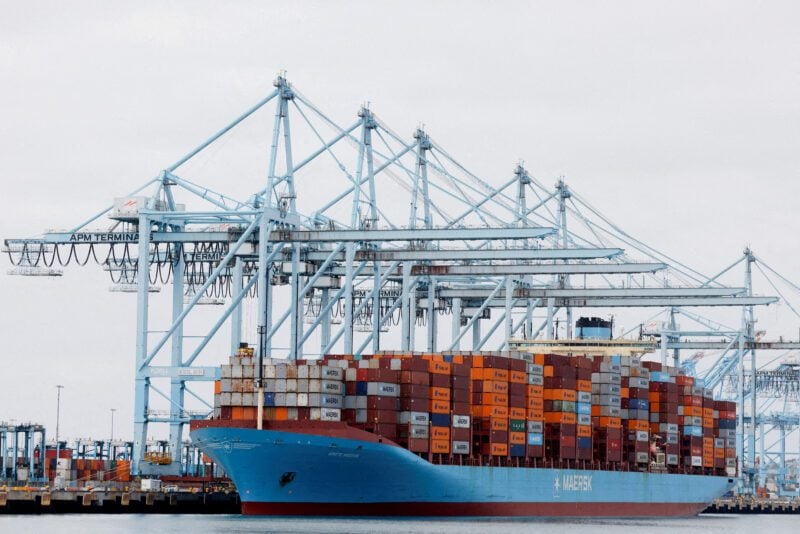
Third-quarter carrier rates experienced a notable decline of 3.3% per package. However, the actual savings realized by operators were significantly less, capturing only about 0.6% of the potential reduction. This disconnect isn’t a result of contract renegotiations but rather a fundamental shift in the nature of shipments themselves. Heavier packages, a demand for faster service levels, and an increasing volume of residential deliveries have collectively eroded the benefits of lower carrier rates.
Table of Contents
Eric Lemus, vice president of strategy and analytics at Deposco, highlighted these trends, noting that while costs for packages under five pounds did decrease, a surge in volume for packages weighing between 11 and 20 pounds effectively nullified much of this relief. This shift suggests consumers are consolidating orders to capitalize on volume-based discounts, leading to larger, heavier shipments.
Shifting Consumer Behavior and Economic Indicators
Despite prevailing soft consumer sentiment readings, gross merchandise value (GMV) growth closed the third quarter at an impressive 11.7%. Lemus pointed out a consistent divergence between survey-based sentiment measures and actual observed spending behavior over the past two years. He strongly advises operators to anchor their forecasts to tangible order volumes rather than relying solely on sentiment indices.
“Don’t rely 100% on those consumer sentiment surveys. Look at your actual order volumes, look at your actual demand, and make a decision going forward based on that to forecast your business because there’s noise — there can be noise in the data around consumer sentiment surveys,” Lemus advised.
Inventory Risks and Peak Season Pressures
Inventory management presents a significant layer of risk as the industry heads into the critical peak season. Brands entered this period holding approximately 94 days of inventory, while third-party logistics providers (3PLs) managed 91 days. This slight advantage for brands, coupled with accelerating sales velocity, elevates the risk of stockouts during Cyber Week and the broader fourth quarter.
Restocking efforts intensified in the final two weeks of September. However, Lemus believes operators may have initiated these restocking efforts too late to fully meet the anticipated Q4 demand. This timing issue could exacerbate inventory challenges and lead to increased reliance on expedited shipping.
Geographic Positioning and Margin Compression
The three-day inventory advantage brands hold over 3PLs becomes particularly crucial for geographic positioning. Brands that depend on 3PL partners for geographical distribution risk having stock located in suboptimal areas. This can force them to incur elevated expedited service rates to fulfill orders across wider zones, directly impacting profit margins even if revenue growth remains robust.
“You have one facility that’s a stockout and you have an order in that geographic location, but to fulfill the order … operators [are] paying higher service delivery rates,” Lemus explained, predicting this dynamic will compress profit margins.
Navigating Q4: Key Signals and Carrier Strategies
Looking ahead to the fourth quarter, Deposco is monitoring four primary signals: a decrease in new orders accompanied by slightly larger basket sizes; rising peak shipping costs relative to Q3; persistent fuel surcharge volatility; and inventory drawdowns driven by sales velocity. To mitigate rate pressures, Lemus recommends that operators utilize a minimum of two to three carriers. He also noted the increasing role of alternative carriers outside the major four, as shippers actively diversify their logistics partners.
The trend towards heavier packages and faster delivery speeds echoes advancements seen in high-performance computing, where optimizing data flow is critical. For instance, technologies like those enabling faster AI training data generation, such as NVIDIA Cosmos Data Factory, highlight the industry’s drive for efficiency and speed, a principle also at play in optimizing shipping logistics.
Q4 Outlook and Strategic Considerations
Overall, indicators suggest a solid, though not extraordinary, fourth quarter. Lemus attributes the current lean inventory levels more to higher interest rates making capital-intensive stock less attractive, rather than an expectation of weaker demand. This distinction is a critical factor for operators to weigh carefully as the holiday selling season accelerates.
The strategic deployment of multiple carriers and a keen eye on actual order volumes over sentiment surveys will be crucial for navigating the complexities of Q4. Understanding the true cost drivers behind shipping, beyond just the base carrier rates, is essential for maintaining profitability in a dynamic market.
Key Takeaways:
- Q3 carrier rates fell 3.3% per package, but shipment mix shifts — heavier weights, faster services, more residential stops — left operators with only 0.6% in realized savings.
- Sales GMV grew 11.7% in Q3 despite weak consumer sentiment surveys, underscoring a two-year divergence between observed spending and survey-based indicators.
- Brands held 94 days of inventory vs. 91 for 3PLs entering peak, raising stockout risk and likely pushing Q4 shipping costs higher as operators pay premium rates to fulfill mislocated stock.
Source: FreightWaves Supply Chain Tech